This post is also available in:
Corn Island Real Estate Financing Options for Foreign Buyers
Dreaming of turquoise water, fresh lobster, and barefoot mornings on Big or Little Corn Island? Many foreign buyers share that vision. Yet one question always rises first: how does corn island real estate financing actually work?
Cash still dominates the islands. However, realistic alternatives exist in 2026. This guide walks you through every practical path. You will see what works for non-residents, what banks expect, and how seller deals often unlock the best opportunities. Along the way we sprinkle in the lifestyle that makes the investment feel worthwhile.
Picture yourself flying into Corn Island’s tiny airport. The plane banks over white sand and coral reefs. Within an hour you could be snorkeling or sipping a cold drink under palm trees. That same lifestyle becomes yours once the paperwork clears. Let’s make the numbers work so the dream stays real.
Why Corn Island Real Estate Financing Matters More Than Ever
Tourism keeps climbing. New flights and better ferry links bring more visitors every season. Property values respond with steady appreciation. At the same time, short-term rental demand from divers and couples stays strong. Many owners cover holding costs and still pocket extra income.
Foreigners enjoy full ownership rights in Nicaragua. No residency is required to buy. Corn Island sits outside the restricted border zones, so the process stays clean. Still, traditional mortgages remain selective. Understanding your real options protects both your budget and your peace of mind.
The islands themselves reward early action. Limited land supply on Little Corn and desirable hillside or beachfront spots on Big Corn create natural scarcity. Smart corn island real estate financing lets you move while good inventory remains available.
Cash Purchases Remain the Fastest Route
Most successful foreign buyers still arrive with cash. Sellers prefer clean, quick closings. Offers backed by verified funds often win against competing bids. Closing can finish in 30 days or less when title work is clean.
Cash also removes interest costs and lengthy bank reviews. You gain full control from day one. Many buyers free capital by selling assets at home or drawing from savings and investments. Others refinance a primary residence before they travel south.
If full cash feels heavy, partial cash plus creative terms still gives you strong negotiating power. Corn Island Realty regularly helps clients structure these hybrid deals.
Seller Financing: The Most Popular Practical Option
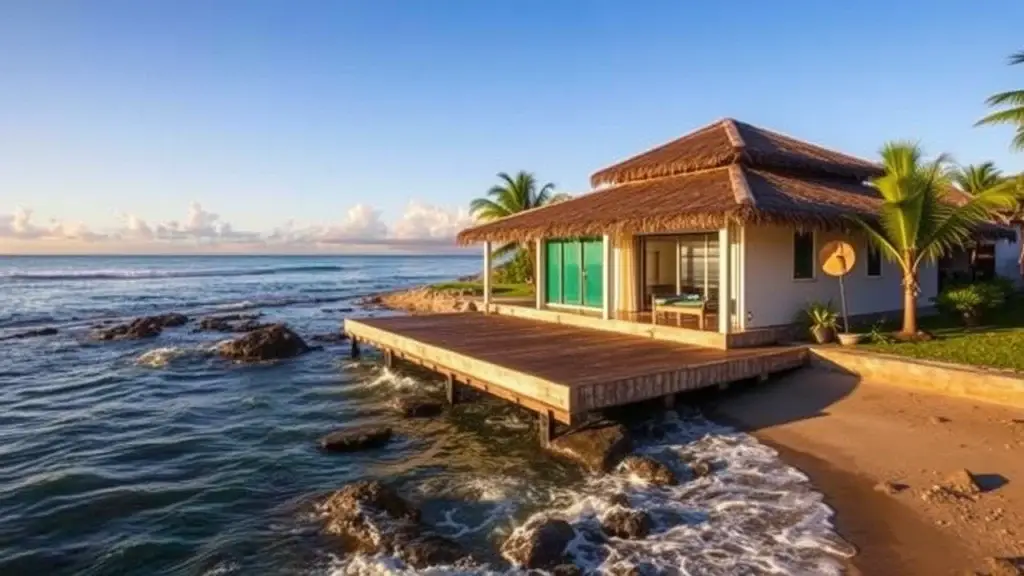
Seller financing thrives on both islands. Many owners prefer monthly payments over a single lump sum. Typical deals ask for 30–50 percent down. The balance spreads over one to five years. Interest rates, when charged, often stay reasonable compared with local banks.
You negotiate the schedule directly with the seller. A local notary records the agreement properly. Title usually transfers only after the final payment, protecting both sides. This route skips bank committees entirely. It works especially well for beachfront lots and smaller homes that local lenders sometimes hesitate to finance.
Always review every clause with a bilingual attorney. Clear payment dates, late fees, and default terms keep the relationship smooth. Many of our clients close seller-financed purchases and start enjoying their porches within weeks.
Local Nicaraguan Bank Loans: Possible but Selective
Some banks will consider foreign applicants. Banpro, Banco LAFISE, and BAC Credomatic lead the list. Approval depends heavily on documentation and your overall profile.
Expect down payments of 30–50 percent for most non-residents. Interest rates in U.S. dollars commonly fall between 8 and 13 percent. Loan terms usually run 10–15 years, though stronger files sometimes reach longer periods. Permanent residency improves both rates and loan-to-value ratios.
Banks want proof of stable income, foreign tax returns, bank statements, and a clean credit history from your home country. A local power of attorney or representative often helps with paperwork and payments. The full process typically takes four to eight weeks once documents are complete.
Remote Caribbean properties can face extra scrutiny. Lenders prefer easily valued and resalable homes. Beachfront or hillside houses with clear titles stand the best chance. Work with an experienced local team that already knows the underwriters.
Home-Country and International Financing Alternatives
Many foreign buyers prefer funding from their own country. A home equity line of credit (HELOC) or cash-out refinance on a primary residence often delivers lower rates than Nicaraguan banks. Personal loans or portfolio lines of credit also appear in successful purchases.
International private lenders sometimes step in for larger deals. These options keep the collateral outside Nicaragua and simplify currency questions. You still transfer funds cleanly for the purchase. Always confirm tax and reporting rules in your home jurisdiction before you draw the money.
This route pairs beautifully with a modest seller-finance balance. You bring strong cash to closing while stretching the remaining payments over a short period.
Step-by-Step Path to Secure Corn Island Real Estate Financing
Start with a clear conversation about your goals and timeline. Contact the team at Corn Island Realty. We map the realistic options that match your situation.
Next, gather core documents early. Passport copies, recent bank statements, tax returns, and proof of income speed every process. If you plan a bank approach, request a foreign credit report in advance.
Then tour properties in person or via live video. Review current listings that fit your budget and financing style. Once you choose a favorite, submit a written offer. Include your preferred payment structure.
Hire a trusted Nicaraguan attorney for title due diligence. The search should cover at least 30–40 years of ownership history, liens, and any coastal or indigenous claims. On Corn Island this step is essential because older titles can contain surprises.
Open an escrow account when the offer is accepted. Funds release only after conditions are met. Sign the final deed before a notary. Registration completes the transfer. Most clean deals close in 30–60 days.
Throughout the journey we coordinate bilingual support, local notaries, and trusted lenders when needed. You stay informed at every stage.
Realistic Costs and Smart Tips for 2026
Budget an extra 3–6 percent for closing costs, notary fees, registration, and attorney work. Transfer taxes and stamp duties appear in the final accounting. Annual property taxes remain very low, often under one thousand dollars for a typical home.
Run the full numbers before you commit. Factor in potential rental income against any loan payments. Well-managed vacation homes on Corn Island frequently generate solid seasonal returns. Explore our vacation rental management services to see how the numbers can work for you.
Always verify the title thoroughly. Coastal properties need proper setbacks from the high-tide line. A professional survey confirms exact boundaries. These steps protect your long-term enjoyment and resale value.
The Lifestyle That Makes Financing Worthwhile
Financing decisions feel different when you picture daily life on the islands. Wake to ocean breezes and the sound of waves. Walk five minutes to a quiet beach. Snorkel over healthy reefs before lunch. Order fresh lobster or grilled fish that still tastes of the sea.
Evenings bring soft Caribbean light and conversations with neighbors who still greet each other by name. Weekends might include a boat trip between Big and Little Corn or a simple hammock afternoon. Many owners spend part of the year here and rent the rest. The combination of personal use and income softens the monthly obligations.
Infrastructure continues to improve. More reliable flights and better internet support both tourism and remote work. The relaxed pace remains the real draw. You trade traffic and winter for palm trees and warm water.
Learn more about island life and ownership rules in our Nicaragua real estate FAQs and the full Corn Islands overview. For broader market context, see our guide to Nicaragua real estate on Corn Island.
External Resources for Further Reading
Compare official bank programs at Banpro, Banco LAFISE, and BAC Credomatic. For tourism and island updates, visit the official Visit Nicaragua portal.
Ready to Explore Your Corn Island Real Estate Financing Options?
Corn island real estate financing does not have to stay a mystery. Cash, seller terms, selective local banks, and home-country equity all create workable paths. The right structure depends on your timeline, down-payment comfort, and long-term plans.
Our team at Corn Island Realty lives and works on the islands. We introduce you to trusted attorneys, notaries, and financing contacts. We also help you evaluate rental potential so the numbers support the lifestyle you want.
Browse current properties for sale. Then reach out through our contact page. Tell us about your ideal budget and preferred payment style. We will map the clearest route to your own piece of Caribbean paradise.
The turquoise water is waiting. Let’s make the financing piece simple so you can start planning the first sunset from your own porch.